
Mezzanine Finance: topping up the development stack
Second-charge development funding that sits above senior debt and below your equity, reducing the cash you put in, in exchange for a higher rate on that slice.
Talk to Ashley about your scheme
Mezzanine finance sits between senior debt and the developer's own equity. The senior lender takes a first charge and funds most of the scheme. The mezzanine lender funds part of the gap between that and total cost, taking a second charge behind the senior and accepting that it gets paid only after the senior is paid in full.
It is expensive, it is heavily documented, and it has become considerably less common than it was. Only four of the 67 lenders we track (our wider panel runs to over 120 lenders across all product types) offer it, against 39 offering senior development debt. The reason is straightforward: stretched senior facilities now reach 90% of cost at 26 lenders on our index, which is exactly where mezzanine used to live. The layer has largely been absorbed.
Where it still works, it works well. This page covers what the four lenders want, how it is really priced, the intercreditor deed that governs everything, what a share pledge means for you personally, and what happens on a default.
The four lenders, and what they want
The range is wider than the small number suggests.
| Facility size | Combined leverage | Term | |
|---|---|---|---|
| Smallest | £100,000 to £1m | 85% of cost, 70% of GDV | 24 months |
| Mid market | £200,000 to £6m | 90% of cost, 75% of GDV. Super mezzanine to 95% of cost and 80% of GDV | 24 months |
| Prime | £1m to £20m | 90% of cost, 75% of GDV | 36 months |
| Institutional | £3m to £15m per project | 85% of cost, 70% of GDV | 36 months |
Minimum deal size runs from £100,000 at the small end to £3m at the institutional end, where there is also a minimum gross development value of £15m. If your scheme sits below that, two of the four are unavailable before anything else is considered.
A senior lender they are comfortable sitting behind. Mezzanine lenders vet the senior terms carefully and will decline a deal because of the senior facility rather than because of the scheme. They are looking at the senior's enforcement rights, the default triggers, the cost overrun obligations and whether the senior will agree a workable intercreditor deed at all. A senior facility with a tight material adverse change clause and no cure rights for a junior lender is a problem.
Profit margin after all finance costs. The usual test is 15% to 20% on cost, or 15% to 20% on gross development value, measured after every finance cost including the mezzanine itself. This is the test that kills most mezzanine enquiries, because by the time you add a second layer at 18% to 20% the margin has gone.
Experience. Generally stricter than senior lenders, because the mezzanine lender is taking first loss. Expect two or more completed schemes of comparable size and type. One of the four accepts first time developers, which is unusual.
Real equity from the developer. Mezzanine fills part of the gap, not all of it. Even super mezzanine products at 95% of cost leave 5% with you, and most lenders want more.
Sector fit. One of the four lends on prime property only. Another is residential development specific.
How mezzanine is really priced
Three components, and the third is the one that decides whether the deal makes sense.
The coupon. Published pricing across the four runs from SONIA plus 10%, which at a SONIA of 3.73% in October 2026 is about 13.7% a year, up to a stated "from 20% a year" at the smaller end. Call the working range 14% to 20%, usually rolled up rather than serviced, because a development scheme produces no income.
The arrangement fee, typically 1.5% to 2% of the mezzanine facility.
The exit fee, and this is where the real cost sits. Mezzanine exit fees are frequently charged as a percentage of gross development value rather than of the loan. On a large slice that is reasonable. On a small slice it is brutal, because it is a fixed number against a small loan.
What a 1% exit fee on GDV actually costs
A £1.6m scheme. A 1% exit fee on GDV is £16,000 whatever the mezzanine slice is. At an 18% coupon over 18 months:
| Mezzanine slice | Interest | Arrangement | Exit fee on GDV | Total | All in, per year |
|---|---|---|---|---|---|
| £55,000 | £14,850 | £825 | £16,000 | £31,675 | 38.4% |
| £100,000 | £27,000 | £1,500 | £16,000 | £44,500 | 29.7% |
| £200,000 | £54,000 | £3,000 | £16,000 | £73,000 | 24.3% |
| £350,000 | £94,500 | £5,250 | £16,000 | £115,750 | 22.0% |
| £500,000 | £135,000 | £7,500 | £16,000 | £158,500 | 21.1% |
Calculate the same exit fee on the loan instead and the all-in cost is 19.7% a year at every slice size, because every component then scales with the loan.
So on a £55,000 slice, an exit fee on GDV rather than on the loan takes the all-in cost from 19.7% to 38.4% a year. Same coupon, same term, same lender. The only difference is one line in the term sheet. On that slice, 1% of GDV is 29% of the loan.
"Ask what the exit fee is calculated on before you ask what the rate is. It is the single most important number in a mezzanine offer and it is the one developers skim past. If the answer is GDV and your slice is small, the deal is probably not worth doing."
Profit share instead of, or alongside, a coupon
Some mezzanine is structured as a lower coupon plus a share of scheme profit, commonly 20% to 50% of profit above a hurdle. That shifts risk to the lender and can be cheaper if the scheme underperforms, and considerably more expensive if it outperforms. Model it at your base case and at your upside before choosing, because the two structures diverge sharply at the top end.
Mezzanine against stretched senior, worked
This is the comparison that matters, and it uses the same scheme as our senior debt page: total cost £1,100,000, gross development value £1,600,000, 18 months, £500,000 of gross profit before finance.
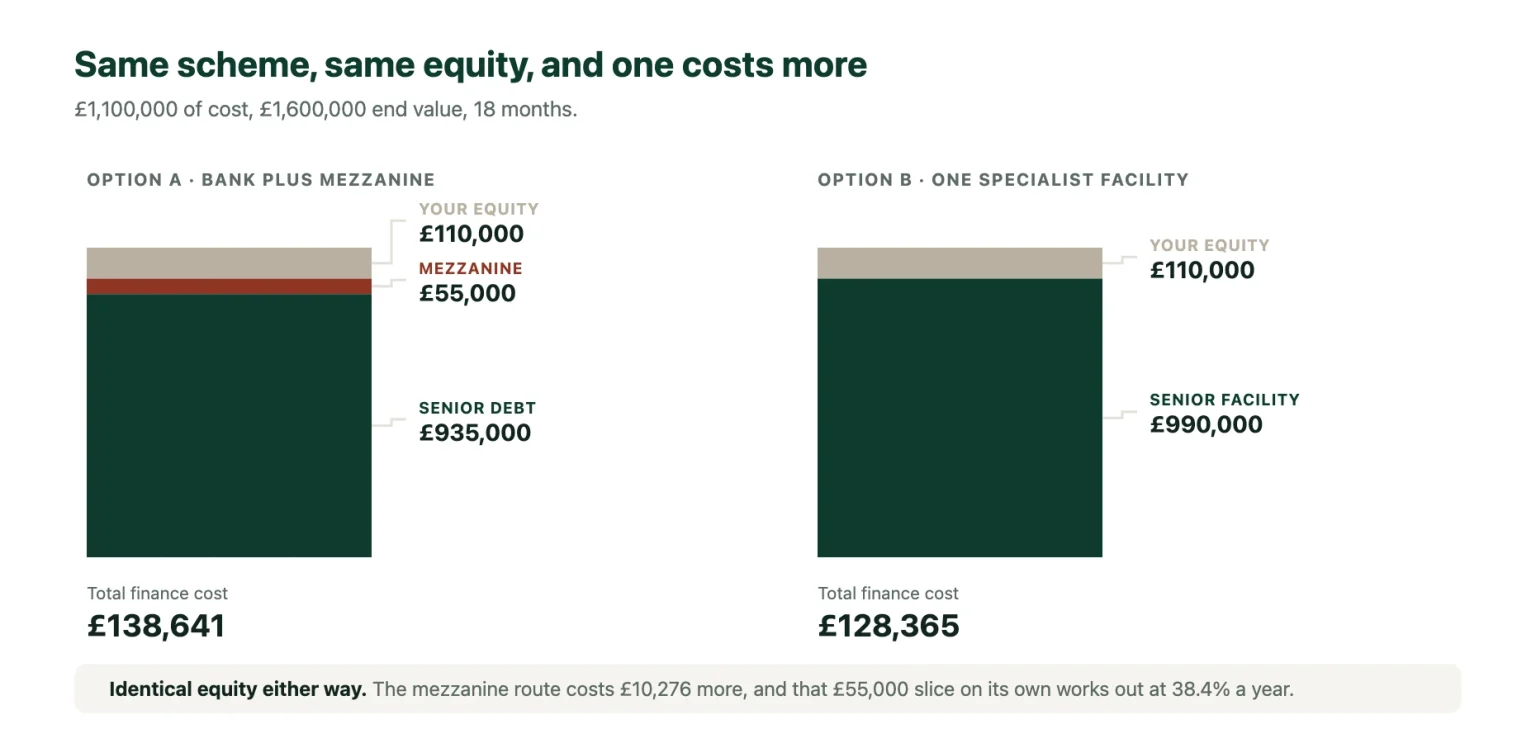
Option A: a bank at 60% of GDV and 85% of cost, topped up with mezzanine to 90% of cost.
| Senior facility | £935,000 at base plus 5%, 1% arrangement, 1% exit |
| Mezzanine | £55,000 at 18%, 1.5% arrangement, 1% exit on GDV |
| Senior interest and fees | £106,966 |
| Mezzanine interest and fees | £31,675 |
| Total finance cost | £138,641 |
| Developer equity | £110,000 |
Option B: a specialist at 70% of GDV and 90% of cost, in one facility.
| Facility | £990,000 at base plus 6.5%, 2% arrangement, no exit |
| Interest and fees | £128,365 |
| Total finance cost | £128,365 |
| Developer equity | £110,000 |
Identical equity. Option A costs £10,276 more.
| Option A | Option B | |
|---|---|---|
| Profit after finance | £361,359 | £371,635 |
| On cost | 32.9% | 33.8% |
| On GDV | 22.6% | 23.2% |
And the £55,000 mezzanine slice, measured on its own, costs 38.4% a year once the GDV exit fee is counted.
On an ordinary scheme of this size, stretched senior beats bank plus mezzanine on cost, on complexity and on time. One facility, one lender, one set of legals, no intercreditor deed, no share pledge. That is why only four lenders still offer mezzanine while 26 offer 90% of cost on a single facility.
When mezzanine still wins
When the senior cannot go higher. If the best senior offer on the table is 60% of GDV and there is no stretched senior option for your scheme, mezzanine is the only way to bridge the gap short of equity.
When the slice is large enough. The table above shows the all-in cost falling from 38% to 21% as the slice grows. Above roughly £300,000 the fixed exit fee stops dominating and mezzanine starts to look like what it claims to be.
When the scheme is too big for stretched senior. Above £15m or £20m of GDV the stretched senior lenders thin out, and senior plus mezzanine becomes the normal shape rather than the expensive alternative.
When the alternative is giving away equity. Mezzanine at 20% a year on an 18 month scheme costs 30% of the slice. A joint venture partner taking 40% of the profit on a scheme making £500,000 costs £200,000. Compare the actual numbers rather than the headline rates.
When you cannot raise the cash any other way and the scheme still clears the margin test afterwards. That last clause is the whole question.
The security structure
Mezzanine lenders secure their position in two ways, usually both at once.
A second legal charge over the property, ranking behind the senior. On its own this is weak security, for the reasons in the waterfall section below, and every mezzanine lender knows it.
A share pledge or share charge over the SPV, meaning the company that owns the site. This is the security that actually matters, and it is why mezzanine documentation is heavier than a second charge alone would require.
What a share pledge means
You pledge the shares in the development company to the mezzanine lender. On an event of default the lender can enforce the pledge and take ownership of the shares, which means it owns the company, which means it controls the property, the planning, the building contract and the bank accounts.
Why lenders prefer it. Enforcing a second charge over property is slow, requires the senior lender's cooperation, and realises value only after the senior is paid. Enforcing a share pledge is faster and gets the lender control of the asset rather than a claim against it. The property never changes hands, so no sale is required.
Three things developers underestimate about it:
You lose the whole company, not just the scheme. If the SPV holds anything else, a second site, retained units, cash, it goes with the shares. Keep one scheme per company, which is good practice anyway.
It can happen faster than a repossession. There is no court process for enforcing a share pledge in the way there is for taking possession of a home. The documentation is designed to make it quick.
It usually sits alongside personal guarantees, not instead of them. The share pledge gives the lender the asset. The guarantee gives it a claim against you for any shortfall. Expect both.
And the clause that governs whether it can actually be used. Almost every senior facility agreement contains a change of control event of default. Enforcing a share pledge is a change of control, so doing it would trigger a default under the senior facility, which defeats the point. The intercreditor deed has to permit it expressly, usually with the senior lender's prior consent or on conditions. If the intercreditor does not deal with this, the share pledge is decorative. A mezzanine lender that has not negotiated it has not done its job, and a developer who assumes it means nothing has misread the position.
The intercreditor deed
This is the document that governs the relationship between the two lenders. You are a party to it, but it is not written for you, and its terms will determine what happens to you in a difficult scheme far more than your own facility agreements will.
Payment blocks
What it is. The senior lender's right to stop you paying the mezzanine lender anything while something is wrong.
When it bites. A senior event of default generally triggers a block. Senior lenders typically want potential defaults to count as well, which is a much wider trigger.
What a well negotiated deed looks like. Mezzanine lenders push to limit blocks to actual defaults arising from financial difficulty and within the borrower's control, excluding minor technical and administrative breaches. They also argue that misrepresentation, information undertakings, general undertakings, material adverse change, unlawfulness and small creditor process events should not on their own trigger a block.
Duration is the key term. A block that runs until the default is remedied or waived can last indefinitely. The negotiated position is a block that lifts automatically after a defined period, commonly 120 to 180 days, with payments resuming unless the senior has accelerated and begun enforcement. A good deed also stops the same default triggering a fresh block repeatedly.
Why you should care. A payment block does not reduce what you owe the mezzanine lender. Interest keeps accruing, usually at a default rate, and it rolls up. A 180 day block on a 20% facility adds a tenth of the balance before anything is resolved.
Standstill
The senior lender's right to prevent the mezzanine lender from enforcing its security for a period, even where the mezzanine facility is itself in default. The point is to give the senior time to work the scheme out without a junior creditor forcing a sale.
Standstill periods are negotiated by reference to the type of default and commonly run in tiers, with a shorter period for a payment default and longer for other breaches. During a standstill the mezzanine lender can usually still accelerate its own debt. It just cannot act on the security.
The right to cure
A well advised mezzanine lender will have the right, though not the obligation, to cure a curable default on your behalf. It pays what you have failed to pay, the senior default goes away, and the amount advanced is added to the mezzanine debt.
This is a genuine benefit to the developer, because a mezzanine lender with a cure right has both the ability and the incentive to keep the scheme alive rather than watch the senior enforce. Check it is there.
Who can enforce, and when
The senior lender controls enforcement in practice. The deed will set out whether and when the mezzanine lender can act independently, whether it needs consent, and what happens to the proceeds.
Purchase options. A sophisticated mezzanine lender will negotiate the right to buy out the senior debt at par on an enforcement event, which converts it into the senior lender and gives it control. On larger deals this is common. On smaller ones it often is not.
Default and the waterfall
The starting point is sequential. Enforcement proceeds pay the costs of enforcement, then the senior debt in full including interest, fees and default interest, then the mezzanine debt, then you.
What that means in practice. On the worked scheme above, senior debt at enforcement might be £1,000,000 including rolled interest, with mezzanine at £70,000. If the scheme sells for £1,200,000 on a forced basis against a £1,600,000 GDV, which is a 25% discount and entirely ordinary, the senior is covered, the mezzanine is covered, and the developer takes the remainder. If it sells for £1,000,000, the senior is just covered and the mezzanine lender gets nothing at all.
Mezzanine takes the whole loss before the senior takes any. That is the structural fact that explains the pricing, the share pledge, the personal guarantees and the margin test. It is not a lender being greedy, it is a lender in a genuinely exposed position.
How often does it get wiped out? On a scheme that fails properly rather than merely runs late, frequently. The gap between a forced sale value and a gross development value is routinely 20% to 30%, and the mezzanine slice is usually thinner than that gap. The honest way to think about it is that mezzanine is wiped out by any outcome bad enough for the senior to enforce. That is why mezzanine lenders underwrite the scheme harder than the senior does, and why they vet the senior's enforcement triggers so carefully.
What mezzanine lenders negotiate to improve it. Rather than a straight sequential waterfall, a mezzanine lender may seek pro rata sharing of certain proceeds, a modified waterfall giving it a participation before the senior is fully repaid, or a fixed percentage of net proceeds, with 20% to 25% cited as a typical ask. Whether they get it depends on the senior lender and the deal.
And the guarantee. When the security is exhausted, the personal guarantee is what remains. A mezzanine lender wiped out on the asset will pursue it, and unlike the asset there is no waterfall protecting you.
Your questions
What is mezzanine finance in property development?
A second charge facility sitting between senior debt and the developer's equity, funding part of the gap between what the senior lender will advance and total project cost. It is repaid after the senior and it is priced for that position.
What does mezzanine finance cost?
Published coupons across the four lenders we track run from around SONIA plus 10%, roughly 14% a year, up to 20% a year, plus an arrangement fee of 1.5% to 2% and an exit fee. The all-in cost depends heavily on whether the exit fee is calculated on the loan or on gross development value.
Why does the exit fee basis matter so much?
Because an exit fee on GDV is a fixed number regardless of how small your mezzanine slice is. On a £1.6m scheme, 1% of GDV is £16,000. On a £55,000 slice that is 29% of the loan, and it takes the all-in cost from 19.7% a year to 38.4%.
Is mezzanine better than stretched senior?
On an ordinary scheme, usually not. On our worked example, bank plus mezzanine cost £10,276 more than a single stretched senior facility for identical equity, with far more complexity. Mezzanine wins where the senior cannot go higher, where the slice is large, or where the scheme is too big for stretched senior lenders.
Will I have to give a share pledge?
Almost certainly, alongside a second charge and usually personal guarantees. It gives the lender ownership of the development company on an enforcement event, which is faster and more effective than enforcing a charge over the property.
Can the mezzanine lender really take my company?
If the intercreditor deed permits it, yes, and quickly. Worth noting that enforcing a share pledge is a change of control, which would trigger a default under most senior facilities, so whether it can be used at all depends on what the intercreditor deed says.
What is a payment block?
The senior lender's right to stop payments to the mezzanine lender while a senior default subsists. Interest continues to accrue on the mezzanine debt throughout, so a block costs you money even though you are making no payments.
How long can a payment block last?
Indefinitely where it is tied to a default being remedied or waived. The negotiated position is a defined period, commonly 120 to 180 days, after which payments resume automatically unless the senior has accelerated.
Does the mezzanine lender check my senior terms?
Yes, closely, and they will decline over the senior facility rather than the scheme. They are looking at default triggers, enforcement rights, cost overrun obligations, the change of control provisions and whether a workable intercreditor deed is achievable.
What profit margin do I need for mezzanine?
Most mezzanine lenders want 15% to 20% on cost or on gross development value after all finance costs, including the mezzanine. That test, applied honestly, is what rules out most enquiries.
Why do so few lenders offer mezzanine now?
Because stretched senior absorbed it. Twenty six lenders on our index will now go to 90% of cost on a single first charge facility, which is the territory mezzanine used to occupy, and one facility is cheaper and simpler than two.
Related
Got a deal like this on your desk?
Tell us the numbers and we'll tell you honestly what's achievable.
Prefer to put it in writing? Email support@bridgingfinancebroker.co.uk