
Second Charge Bridging Loans: raise funds without touching your mortgage
Keep your existing (probably cheap) first mortgage exactly where it is, and raise short-term funds behind it. How second charges work, when they beat a refinance, and what your first lender has to say about it.
Talk to Ashley about your deal
A second charge bridging loan sits behind an existing mortgage. The first lender keeps its charge and its priority, and the bridging lender takes a second charge over the same property, ranking behind it.
It is the right answer in a specific set of circumstances: where you have equity in a property, you need money quickly, and disturbing the existing mortgage would be expensive or impossible. It is the wrong answer more often than people expect, usually because the available headroom is far smaller than the equity suggests.
Thirty-six of the 67 short-term lenders we track (our wider panel runs to over 120 lenders across all product types) will consider a second charge. Fewer will do it as a standalone deal, and the consent of the first charge lender is the single thing most likely to decide whether the transaction happens at all.
"People ring up with a hundred and sixty grand of equity expecting a hundred and sixty grand. The combined cap and the mortgage balance eat nearly all of it. I would rather tell you that in the first five minutes than in week four."
Why the headroom is always smaller than you think
This is the arithmetic that catches almost everyone, so it is worth doing first.
Second charge bridging is calculated on a combined loan to value, meaning the first charge balance and the new loan added together, measured against the property's value. The maximum is lower than on a first charge, and the existing mortgage comes off the top.
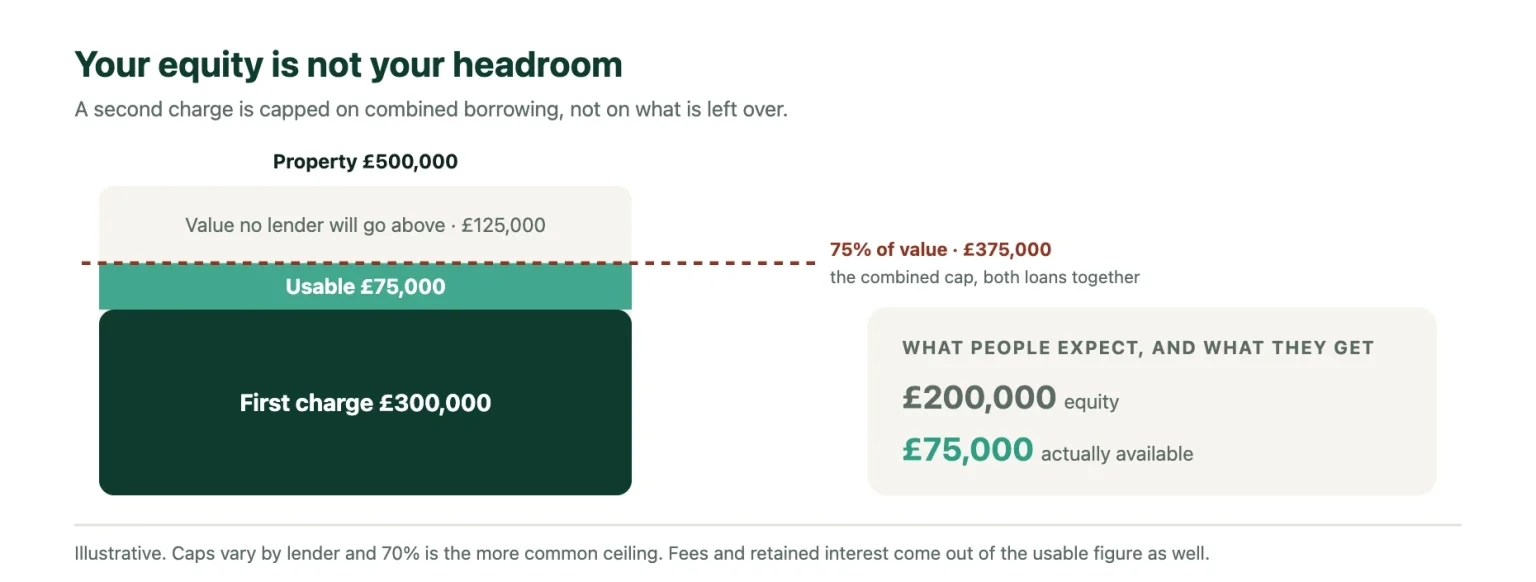
Across the lenders we track, published maximums run:
| Combined LTV cap | How common |
|---|---|
| 55% | By referral at one lender |
| 60% | Several, including one capping at 60% net |
| 65% | Common, and often stated as "including the first charge" |
| 70% | The upper end, including one regulated lender |
| 75% | Rare, and usually with conditions |
Now apply it. Take a property worth £400,000 with a £240,000 mortgage. The owner sees £160,000 of equity.
| At 65% | At 70% | |
|---|---|---|
| Combined ceiling | £260,000 | £280,000 |
| Less the existing mortgage | £240,000 | £240,000 |
| Gross headroom | £20,000 | £40,000 |
| Less 2% arrangement fee | £400 | £800 |
| Less 12 months retained interest at 1% | £2,400 | £4,800 |
| Less legal and valuation costs | about £2,000 | about £2,000 |
| Net reaching your solicitor | about £15,200 | about £32,400 |
£160,000 of equity produces £15,000 to £32,000 of usable money. That is the most important thing to understand before starting, and it is why a good number of second charge enquiries end in the first conversation.
The arithmetic improves sharply as the first charge balance falls. The same £400,000 property with a £150,000 mortgage produces £110,000 of gross headroom at 65%, which is a different proposition entirely.
And some lenders cap the first charge as well. One requires the existing first charge to be no more than 45% loan to value, and to be with a recognised term lender. That is a far tighter test than the combined cap on its own.
The consent process, step by step
The second charge lender needs the first charge lender to acknowledge the new charge and agree how the two rank. Nothing completes without it, and this is where the time goes.
Stage 1. Establish whether consent is even possible. Day one. Not every first charge lender permits a second charge. Many mortgage conditions contain a negative pledge clause prohibiting further charges without consent. Some lenders grant it routinely, some case by case, some never. Finding out which you are dealing with is the first call, not the last.
Stage 2. Submit the request. Days one to three. Usually your solicitor writes to the first charge lender with the details of the proposed second charge: the lender, the amount, the term and the security. Some have a form. Some have an online portal. Some have neither.
Stage 3. Wait. One to six weeks, and that is the honest range. This is the stage that defines the transaction. Consent teams work to their own service levels, which are not published and bear no relation to your deadline. Specialist and short-term lenders are usually quick, because they deal with it constantly. High street banks are the slowest, and building societies vary enormously.
We have had a second charge where our own side was complete in three working days with only the first charge consent outstanding. The lender was ready. The consent was not.
Stage 4. The consent arrives, and it is one of three things. A letter of consent, a deed of priority, or a refusal. All three are covered below.
Stage 5. Execution and completion. Three to seven days. The deed is engrossed, signed by all parties, and completion follows.
Realistic total: three to eight weeks, of which the first charge lender's consent accounts for most of it. Any timeline that assumes a week is assuming the best case at every stage.
How to make it faster
- Ask the question on day one. Before anything else, find out whether the first charge lender consents at all, and what their stated turnaround is
- Submit a complete request. Incomplete requests go to the back of the queue and nobody tells you
- Chase on a schedule, not when you remember. Weekly, in writing, with the reference
- Use a solicitor who has done it before. The consent process is unfamiliar to many conveyancers, and an unfamiliar solicitor loses a fortnight learning it
- Run everything in parallel. The valuation, the second charge lender's legal work and the consent request should all be moving at once. Nothing is gained by sequencing them
Deed of priority, or letter of consent?
Both do a similar job. They are not the same document and the difference matters.
A letter of consent is the first charge lender simply confirming it has no objection to the second charge being registered. Shorter, quicker, cheaper. It does not usually deal with what happens between the two lenders afterwards.
A deed of priority is a formal agreement between the two lenders, signed by both and usually by you, setting out the order in which they rank and, critically, the maximum amount the first charge will rank ahead for. That cap is the point of the document. Without it, the first lender can in some circumstances make further advances that rank ahead of the second charge, eroding the second lender's position after it has already lent.
Most bridging lenders want a deed of priority. Some will accept a letter of consent on a small loan, or where the relationship is known.
Who pays. You do, in every case, and on both sides. Expect:
- The first charge lender's consent fee, commonly £100 to £350. One published tariff shows £250 per application
- The deed of priority fee, commonly £250 to £500. One published tariff shows £350
- The first charge lender's solicitor's costs for reviewing and executing, often £300 to £750
- Your own solicitor's additional costs for handling it
- On a company borrower, a letter of non-crystallisation where there is a floating charge, at around £250
Budget £750 to £1,500 for the consent process as a whole, on top of the normal bridging costs. It is not a formality and it is not free.
A £200,000 house with a £100,000 mortgage on a rate worth keeping, and a builder with one slot free.
Read how it worked →What if the first charge lender refuses?
Refusals happen, and they are rarely negotiable. A lender that does not permit second charges as a matter of policy will not make an exception for you.
The realistic options, in order of preference:
Refinance the first charge away. If the first lender will not consent, move the first charge to one that will, and take the second charge behind the new lender. This costs time and fees, and may trigger early repayment charges, but it solves the problem cleanly. It is frequently the right answer.
Replace both with a single first charge bridge. Pay off the existing mortgage entirely and take one larger first charge bridging loan. Leverage is higher on a first charge, pricing is better, and there is no consent to obtain. The cost is losing the existing mortgage, which matters if it is on a rate you will not get back.
Use a different property. If you own another property with equity, a first charge on that is simpler and cheaper than a second charge on this one.
Take an equitable charge. Covered below. A genuine fallback, with real limitations.
Reconsider the need. If the money is for something that can wait, waiting may be cheaper than any of the above.
What does not work is granting a second charge anyway and hoping. Where the mortgage conditions prohibit further charges without consent, doing it regardless is a breach of the mortgage, which can make the whole balance repayable on demand. No reputable lender will proceed on that basis, and a solicitor will not act.
Equitable charges, and when you would use one
An equitable charge is the recognised fallback where a legal second charge cannot be registered, and several lenders on our index will take one. At least one describes itself as a second, third and equitable charge specialist.
What it is. An equitable charge creates an interest in the property arising in equity rather than a registered legal charge. It is protected at the Land Registry by a notice against the title rather than being registered as a charge.
Why it helps. Creating one does not require the consent of the existing legal chargeholders. That is precisely why lenders reach for it when consent is refused or delayed, or where a lease prohibits a legal charge.
What you give up. Weaker enforcement rights. There is no immediate power of sale. To enforce, the lender has to go to court for an order, which is slower and more expensive. Lenders price for that.
On priority, the position is more nuanced than most people assume. Equitable charges rank between themselves by date of creation, whether or not noted on the register. A later legal charge overrides an equitable charge that was not noted. But an equitable charge that is noted on the register takes priority over a legal charge created afterwards, so a first legal charge does not automatically outrank a noted equitable charge. The order of registration and notice matters, which is why this is a question for a solicitor on your specific title rather than a general rule.
The critical caveat. Avoiding the need for consent is not the same as avoiding the mortgage conditions. If the first charge mortgage contains a negative pledge preventing you from creating further charges of any kind, creating an equitable charge may still breach it. Some lenders taking equitable charges require consent to be evidenced anyway, with one capping equitable charge loans at £250,000 to 65% loan to value and stating that consent must be evidenced.
When you would actually use one. Where the first charge lender is slow rather than opposed and the deadline will not wait. Where the security is leasehold and the lease restricts legal charges. Where the charge is a makeweight over a secondary property rather than the main security. And in restructuring situations where speed matters more than enforcement strength.
When you would not. As a way around a refusal that reflects a genuine prohibition in the mortgage conditions. That is storing up a problem, not solving one.
What happens if the first charge lender repossesses
The second charge lender's position on enforcement is the reason second charges price higher and lend less, so it is worth understanding.
The first charge lender controls the process. If it takes possession and sells, it sells the property, not just its own interest.
The proceeds are applied in order. The costs of sale first, then the first charge lender's debt in full including its interest and costs, then the second charge lender, then anything left to you.
The second charge takes the loss first. If the property sells for less than the combined debt, the shortfall falls entirely on the second charge lender until it is wiped out, before the first lender loses a penny. On a repossession sale, which typically achieves less than an open market sale, that can happen on a surprisingly modest shortfall.
The second charge lender is not powerless. It is entitled to be notified of the first lender's enforcement steps, it can redeem the first charge itself to take control of the sale, and it can apply to the court for an order for sale. Those are real rights, but all of them require money and time.
What this means for you. The second charge lender's weaker position is priced in, which is why combined loan to values are lower and rates are higher. It also means the second charge lender scrutinises your exit harder than a first charge lender would, because it has less margin for error.
What a second charge bridge costs
Rates sit above first charge, typically by 0.15% to 0.40% a month. Published examples across our index: one lender at 0.68% on residential first charge against 0.95% on second charge, a gap of 0.27%. Another at 0.99% first charge against 1.25% second. A third at 0.89% and 0.99% on first charge tiers against 1.04% and 1.09% on second charge tiers.
Broadly, expect 0.95% to 1.30% a month on a second charge against residential security.
Everything else is as a first charge bridge, plus the consent costs above: arrangement fee at 1.5% to 2%, valuation, legal costs on both sides, and in some cases an exit fee. Our rates page breaks down every charge.
Conditions that catch people out
Several lenders attach conditions to second charge lending that are not obvious from the headline:
- The first charge must be a term mortgage, not a bridge. One lender states it explicitly: a second charge will go behind a first charge term mortgage, never behind another bridge
- The first charge must be below a stated loan to value, with one lender requiring no more than 45%
- The first charge must be with a recognised lender, which rules out private and unusual arrangements
- Business purposes only on a main residence, which is how several lenders handle an owner-occupied property without taking it into regulated territory
- Not available standalone. Some lenders will only take a second charge as a makeweight alongside a first charge they already hold
- Lower maximum loan. One lender caps first charges at £1.5m and second charges at £500,000 on the same product
- Regulated second charge bridging is rare. Where the property is your home the loan is regulated whether it is a first or second charge, and only a handful of lenders offer it at all
When a second charge beats the alternatives
Against a further advance from your existing lender. A further advance is cheaper, usually far cheaper. Take it if you can get it. A second charge bridge beats it when the lender has declined, when the purpose is one they will not fund, when the property or your income will not pass their current criteria, or when you need the money in weeks rather than months.
Against a remortgage. A remortgage gives you the cheapest money available. A second charge bridge beats it when your existing mortgage carries early repayment charges that exceed the cost of the bridge, when your existing rate is better than anything available now, when your circumstances have changed such that you would not get the same mortgage today, or when the timescale will not stretch to four to eight weeks.
That second reason is the one that matters most in practice. If you are sitting on a mortgage rate materially below current pricing, disturbing it to raise a modest sum can cost more over the remaining term than a short second charge ever will. Work out the cost of losing the rate before assuming a remortgage is cheaper.
Against a second charge term loan. A regulated second charge mortgage over 10 to 25 years is far cheaper per month than bridging and is the right product where the need is long term. A second charge bridge beats it on speed, on properties a term lender will not take, and where the money is genuinely short term and will be repaid from a defined event.
Against selling something. Sometimes the honest answer. If the second charge produces £15,000 after costs and the need is £60,000, the arithmetic has already told you what to do.
A couple part way through refurbishing their own home, with the first charge staying exactly where it was.
Read the full case study →Common Questions About Second Charge Loans | Bridging Finance Broker
How much can I borrow on a second charge bridge?
Typically 65% to 70% of the property value including your existing mortgage, with a minority going to 75% and some capping at 55% or 60%. Subtract your mortgage balance from that ceiling to find the gross headroom, then subtract the fee and the retained interest to find what you actually receive.
Do I always need the first lender's consent?
For a legal second charge, yes. An equitable charge can be created without it, but if your mortgage conditions prohibit further charges, creating one may still breach them.
How long does second charge consent take?
One to six weeks, depending entirely on the first charge lender. Specialist lenders are fast, high street banks are slow, building societies vary. It is almost always the longest item in the transaction.
What does the consent process cost?
Budget £750 to £1,500 all in. Published figures include £250 for an application for consent, £350 for a deed of priority and £250 for a letter of non-crystallisation, plus the first lender's solicitor's costs.
Can I get a second charge bridge on my own home?
Yes, but it will be a regulated loan, and only a small number of lenders offer regulated second charge bridging. Several others will lend on a main residence for business purposes only.
Can I take a second charge behind a bridging loan?
Rarely. At least one lender states plainly that it will only sit behind a first charge term mortgage, never behind another bridge. Where it is possible at all, expect it to be treated as a mezzanine arrangement with an intercreditor deed.
What if my first lender says no?
Refinance the first charge to a lender that permits it, replace both with a single first charge bridge, use a different property, or consider an equitable charge. Proceeding without consent where it is required is not an option.
Is a second charge riskier for me than a first charge?
The risk to you is the same in one respect: you can lose the property either way. What changes is the cost, because the lender's weaker position is priced in, and the flexibility, because there are fewer lenders and tighter criteria.
Will a second charge affect my existing mortgage?
It should not change its terms, but your lender will know about it, and it may affect future applications for further borrowing with them. It also means any future further advance they make may rank behind your second charge, which is one reason some lenders refuse consent in the first place.
What is the difference between a deed of priority and a letter of consent?
A letter of consent simply says the first lender does not object. A deed of priority is a formal agreement between both lenders setting out the ranking and, crucially, capping the amount the first charge ranks ahead for. Most bridging lenders want the deed.
Why is a second charge more expensive than a first charge?
Because on enforcement the second charge lender is paid only after the first charge lender has been repaid in full, including its costs. If the property sells short, the second charge absorbs the whole loss before the first lender loses anything. That weaker position is priced in.
Related
Got a deal like this on your desk?
Tell us the numbers and we'll tell you honestly what's achievable.
Prefer to put it in writing? Email support@bridgingfinancebroker.co.uk