
Senior Development Debt: the foundation of every funding stack
The core development loan: first charge, lowest rate in the stack, funding land and build. How pricing, leverage and lender appetite actually work in the current market.
Talk to Ashley about your scheme
Senior debt is the first charge facility that funds most of a development scheme. It is the largest layer of the funding stack by a distance, and it is what most developers end up with regardless of what they came in asking about. Mezzanine, joint venture equity and the rest sit on top of it, and every one of them is shaped by what the senior lender will and will not do.
Thirty nine of the 67 short-term lenders we track (our wider panel runs to over 120 lenders across all product types) offer development finance. They are not interchangeable. A clearing bank and a family office lending against the same scheme will produce different leverage, different pricing, a different process and, when the scheme slips, very different behaviour. That last point is the one nobody writes about honestly, and it matters more than the rate.
How a facility is sized, drawn and monitored is covered on our development finance page. This page is about who the lenders are, how they price, what the agreement actually commits you to, and how to choose.
Who the lenders actually are
Six types, and the type tells you more about what you will get than the brand does.
Clearing banks
Where the money comes from. Customer deposits, the cheapest funding there is.
What they offer. The lowest pricing in the market and the most conservative terms. Expect loan to gross development value in the 55% to 60% range and loan to cost well below the market median, which means substantially more of your own cash.
How they behave. Relationship led. They usually want your wider banking, they want a track record with them specifically, and they want a developer who looks like a going concern rather than a project. Credit approval goes through a full committee.
Speed. The slowest. Three to six months from first conversation to drawdown is normal, and that is not a criticism, it is how the process works.
When a scheme slips. This is where the type matters most. A clearing bank's problem loans move to a workout or business support team who did not write the facility and do not know you. The relationship you built with the lending manager does not transfer with the file. Banks are not quick to enforce, but they are slow to agree anything, and a paused drawdown on a live site is expensive.
Challenger and specialist banks
Where the money comes from. Deposits, but from institutions built for this kind of lending rather than for retail banking.
What they offer. Middle of the market pricing with genuinely competitive leverage. One on our index publishes 65% of gross development value alongside 90% of cost, with a £1m minimum facility, which is a typical shape. The minimum is the thing to note, because small schemes frequently do not fit.
How they behave. Commercially minded, with real development expertise in the credit team, but still bank-regulated, which means capital rules and a formal credit process. More predictable than a fund, less flexible than a family office.
Speed. Six to twelve weeks.
When a scheme slips. Generally pragmatic, with people who understand construction. The regulatory framework limits how far they can bend.
Debt funds
Where the money comes from. Institutional capital raised specifically to lend, from pension funds, insurers and similar.
What they offer. Pricing quoted as a margin over base, typically in the 5% to 6.5% range. Leverage at 70% to 75% of gross development value. Larger schemes, and several have minimum facilities of £500,000 to £1m.
How they behave. They have money they are required to deploy, which makes them hungry and commercially responsive. They are also covenant-driven, because they answer to investors who measure them on portfolio performance.
Speed. Four to eight weeks, and faster where authority is delegated.
When a scheme slips. Decisive in both directions. A fund will restructure quickly where the economics still work and enforce quickly where they do not. There is no sentiment and no relationship banking. You get a commercial answer fast, which is better than a slow one, but it may not be the answer you want.
Specialist development lenders
Where the money comes from. A mix of institutional facilities and their own capital.
What they offer. The highest leverage on our index, with loan to cost of 90% and occasionally above, and the widest appetite for schemes banks will not touch. Pricing either as a margin over base or as a flat monthly rate.
How they behave. Built for speed and for schemes with a wrinkle. More willing on first time developers, unusual sites, conversions and part-complete rescues. The flexibility is real and it is priced for.
Speed. Three to eight weeks, and several will issue credit-backed terms within days.
When a scheme slips. Usually commercial, because they deal with it constantly. Their facility agreements tend to give them more control, so they engage earlier.
Family offices and private balance sheet lenders
Where the money comes from. Their own, which changes everything.
What they offer. Pricing at the top of the range, often as a flat annual rate rather than a margin. One on our index, family owned and lending for 25 years, prices at a flat 9.75% to 13% a year. Leverage varies enormously, because there is no rule book, only a view.
How they behave. The fastest decisions in the market, because there is no credit committee and no investor to persuade. One private balance sheet lender on our index has lent £700m over 921 deals, uses in-house solicitors and does next-day site visits. Another is entirely balance sheet funded and specialises in complex, time-sensitive deals. A third describes itself as a small balance sheet lender using its own cash, funding in as little as 48 hours.
Speed. Days to weeks.
When a scheme slips. Generally the most pragmatic of all the types, and the reason is structural rather than sentimental. It is their own money, a workout costs them more than patience does, and the decision maker who wrote the loan is the decision maker who handles the problem. You deal with the same person throughout.
Building societies
Where the money comes from. Member deposits.
What they offer. Regional focus, modest scheme sizes, and appetite for things the market ignores, including self and custom build. One on our index offers up to 90% of cost and 70% of gross development value over terms to 36 months, which is longer than most of the market.
How they behave. Conservative, mutual, and often willing on a small scheme where the economics are sound but the size does not interest anyone else.
Speed. Variable, generally measured in months.
"Match the lender type to what the scheme actually needs. Plenty of cash and plenty of time, and a bank is the cheapest money you will find. An unusual site, a short timescale or tight cash, and you are buying flexibility and speed, which have a price that shows up on the rate. Then ask what happens if it goes wrong, because that is where the types diverge most and none of them will volunteer the answer."
How pricing is actually built
Development finance is priced two ways, and comparing them means converting one into the other.
Margin over base
The norm among funds, banks and the larger specialists. The rate is the Bank of England base rate plus a margin, and it floats with base.
Across the development lenders we track, published margins run from 4.70% to 6.75% over base. At the base rate of 3.75% as at October 2026, that produces:
| Published margin | All in, per year | Monthly equivalent |
|---|---|---|
| Base + 4.70% | 8.45% | 0.704% |
| Base + 5.00% | 8.75% | 0.729% |
| Base + 5.50% | 9.25% | 0.771% |
| Base + 5.75% | 9.50% | 0.792% |
| Base + 5.95% | 9.70% | 0.808% |
| Base + 6.50% | 10.25% | 0.854% |
| Base + 6.75% | 10.50% | 0.875% |
The thing to understand about margin pricing is that you carry the interest rate risk. On an 18 month facility a base rate rising half a point costs real money, and the facility agreement may also require you to hedge. Check whether there is a floor, because some facilities set a minimum base rate for calculation purposes, which means you lose the benefit of a cut.
Flat monthly or flat annual
Used by private balance sheet lenders and most of the bridging-style development products. The rate is fixed for the term, commonly 0.75% to 1.10% per month, or 9.75% to 13% a year at the private end.
Flat pricing costs more at the headline and transfers the rate risk to the lender. On a long facility in a rising rate environment that can be worth paying for. On a falling rate it is not. Our page on bridging loan rates covers how the same arithmetic works on shorter facilities.
Where the fees sit
- Arrangement fee, typically 1% to 2% of the facility. Banks and funds at the lower end, specialists at the higher. Check whether it is charged on the full facility or the drawn amount, because on a facility you only partially draw that is a material difference
- Exit fee, commonly 1%, and the critical question is what it is calculated on. An exit fee on gross development value rather than on the loan is a much larger number. On a £1.6m GDV scheme, 1% of GDV is £16,000 against 1% of a £990,000 loan at £9,900
- Non-utilisation fee on the undrawn balance with some lenders, with one on our index charging 0.30% per month on tranched facilities
- Monitoring surveyor, paid by you throughout
- Legal costs, both sides, and development documentation is heavier than bridging documentation
A bank quote against a specialist quote
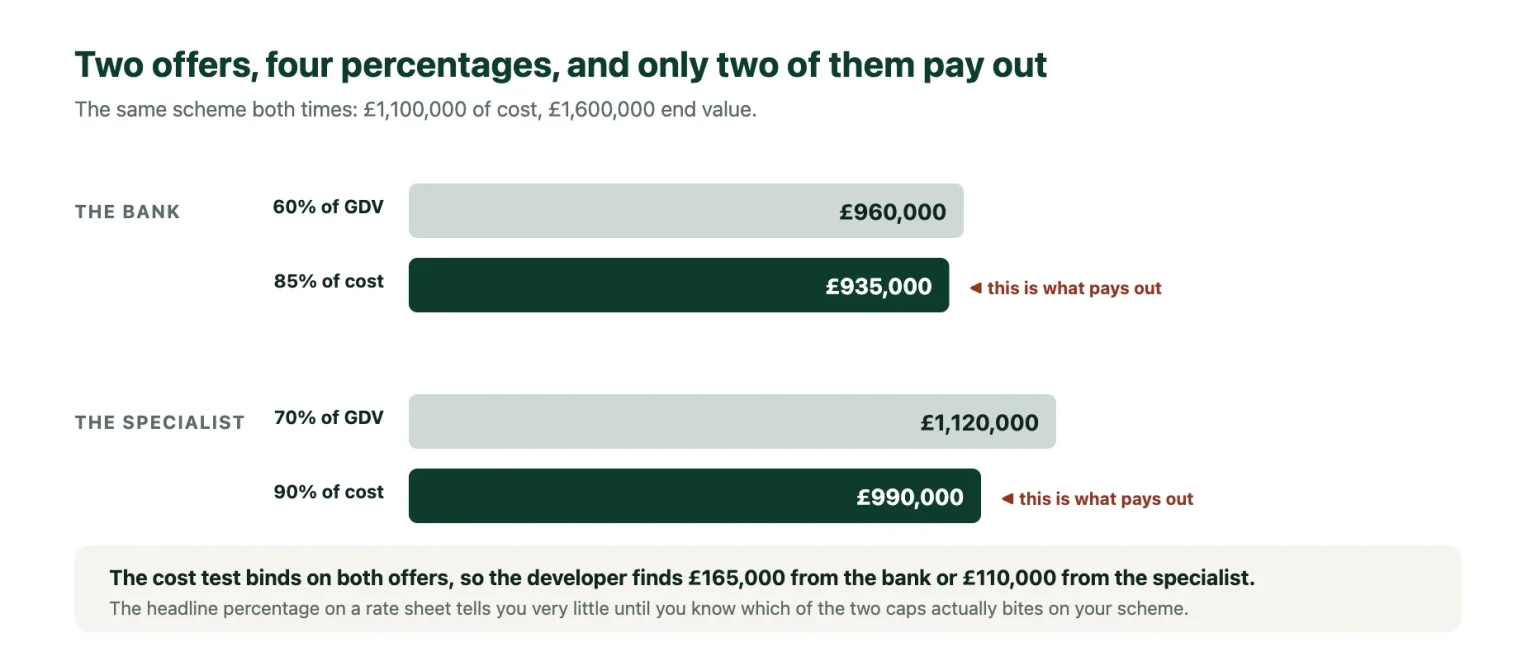
Same scheme, same developer, two offers. Total project cost £1,100,000, gross development value £1,600,000, 18 month term.
The bank offers base plus 5%, so 8.75% a year, at 60% of GDV and 85% of cost, with a 1% arrangement fee and a 1% exit fee.
The specialist offers base plus 6.5%, so 10.25% a year, at 70% of GDV and 90% of cost, with a 2% arrangement fee and no exit fee.
| Bank | Specialist | |
|---|---|---|
| Facility | £935,000 | £990,000 |
| Your equity required | £165,000 | £110,000 |
| Interest over 18 months | £88,266 | £108,565 |
| Fees | £18,700 | £19,800 |
| Total finance cost | £106,966 | £128,365 |
The specialist costs £21,399 more and needs £55,000 less of your money. Both interest figures are calculated on the drawn balance as the build progresses rather than on the full facility, which is how these facilities actually charge.
The number that should decide it
That extra £55,000 of leverage costs £21,399 over 18 months. As an annualised cost on the marginal money, that is 25.9% a year.
The top slice of a stretched senior facility is priced like mezzanine, even though it arrives as one facility at one headline rate. The blended rate hides it.
So the question is not which quote is cheaper. It is what the £55,000 is worth to you. If it is the difference between doing this scheme and doing this scheme plus a deposit on the next one, 26% is cheap. If it is going to sit in your account earning nothing, you have just paid £21,399 for the privilege of keeping it there.
Run that calculation on every stretched senior offer. It is the single most useful thing a developer can do with a term sheet, and almost nobody does it.
Covenants, and what actually breaches them
The facility agreement contains tests you must keep meeting throughout the loan, not just at the outset. These are the ones that bite.
Cost to complete. The most important covenant in development finance and the one most often breached. The lender must be satisfied at every drawdown that the undrawn facility plus your committed equity is enough to finish the scheme. If costs rise, that test fails even though you have made no mistake and missed no payment.
Loan to cost, retested at drawdown. Your facility was sized at 90% of cost. If cost rises and the facility does not, the ratio moves against you and the lender can require you to inject equity to restore it before releasing more money.
Programme milestones and the longstop date. Specific stages by specific dates, with a backstop date for practical completion. Construction delays breach these routinely.
Minimum sales covenants. On larger schemes, a requirement for a number or value of units reserved or exchanged by a date. Common on anything above a handful of units.
Loan to gross development value, retested on revaluation. If the lender revalues and the GDV has fallen, the facility can breach without anything changing on site.
Financial covenants on the borrower and guarantors, typically a minimum net worth or liquidity test.
Equity contribution. Most facilities require your money in first, before the lender advances anything. Some allow it alongside. Very few allow it last.
What happens on a breach
The agreement says: event of default, all monies immediately repayable, default interest, appointment of receivers, step-in. That is what it threatens. What usually happens is different, and the sequence is predictable.
A reservation of rights letter. The lender confirms the breach, states that it is not waiving anything, and continues on that basis. This is standard and not in itself a crisis.
Drawdowns pause. This is the real consequence and the one that costs. Your site is live, your contractor is on programme, and the money stops while the lender considers. A fortnight of paused drawdown on a live site costs far more than any fee.
A waiver, for a fee. Commonly a few thousand pounds, sometimes a percentage, with revised covenants going forward.
A requirement for more equity. The most common outcome on a cost overrun: the lender restores the facility once you have put in enough to satisfy the cost to complete test again.
Repricing or a shortened term, where the lender agrees to continue but on different terms.
Enforcement, which happens where the scheme is not viable rather than merely delayed, or where the developer has stopped communicating.
"Tell the lender before they find out. A cost overrun disclosed in month four with a plan is a waiver conversation. The same overrun discovered by the monitoring surveyor in month eight is a completely different conversation, and the difference is credibility, not arithmetic."
What is in the facility agreement that developers do not read
Development documentation runs to a hundred pages, and most developers read the commercial terms and sign the rest. These are the clauses that matter.
Material adverse change. A clause letting the lender stop lending if, in its opinion, there has been a material adverse change in your position, the scheme or the market. It is subjective, it is the lender's opinion, and it is rarely invoked but devastating when it is. Ask whether it can be narrowed to objective tests.
Cross default. A default under any other facility you or your group has triggers a default under this one, even if the other facility is unrelated and the payment was missed by accident. On a developer with several schemes and several lenders, this links everything together. Ask for a materiality threshold so a small unrelated issue does not cascade.
Step-in rights. The lender's right to take over the scheme and complete it, usually through a receiver or its own appointed contractor. These exist in every development facility, and they are the reason the next clause exists.
Collateral warranties and the right to appoint its own contractor. The lender takes warranties from your contractor and professional team, plus an assignment of the building contract and appointments, so that on a step-in it can instruct them directly. Your contractor has to agree to this, which is why warranties are a condition precedent and why they hold up completions.
Negative pledge. No further charges over the property or the company without consent. This is the clause that blocks mezzanine finance later, and it is why the senior lender's consent, not the mezzanine lender's appetite, is the binding constraint on a second layer.
Restrictions on distributions. You cannot take profit, dividends or director's loans out of the borrowing company until the facility is repaid or specified tests are met. Any developer budgeting personal income from a scheme needs to read this one.
Sale proceeds sweep. How much of each sale goes to the lender. A 100% sweep until the debt reduces to a target means early sales produce no cash for you. Our development exit page covers how much more generous release terms usually get once the build is finished.
Default interest. Commonly 3% to 5% above the normal rate, sometimes more, and it applies from the date of default rather than from when anyone noticed.
Cost overrun obligation. An express obligation on you to fund any overrun, sometimes supported by a parent company guarantee or a cash deposit.
Hedging requirements on floating rate facilities, which carry their own cost.
Conditions subsequent, meaning things you must deliver after completion by set dates. Missing one is a default even though the money has been drawn.
Get a solicitor who does development finance to read it. The commercial terms are negotiable at term sheet stage and almost nothing is negotiable once the documents are in draft, which is why the term sheet deserves more attention than it usually gets.
Speed and process
| Stage | Typical |
|---|---|
| Enquiry to indicative term sheet | 1 to 5 days |
| Term sheet to credit-backed offer | 1 to 3 weeks |
| Valuation and initial monitoring surveyor report | 2 to 4 weeks |
| Legal documentation | 3 to 6 weeks |
| Conditions precedent, including warranties | 1 to 3 weeks |
| Total to first drawdown | 6 to 12 weeks |
Three to four weeks is achievable at the fast end. Three to six months is normal with a clearing bank.
What makes one lender three weeks and another three months
Delegated authority versus full credit committee. The single biggest variable. A lender whose underwriter can approve up to a threshold moves in days. A lender requiring a committee that sits fortnightly, where a deferred paper costs you two weeks and a question costs you four, cannot.
In-house or panel professionals. Lenders with in-house solicitors, valuers or monitoring surveyors save weeks. One private lender on our index uses in-house solicitors and does next-day site visits.
Whether the monitoring surveyor's report is required before or after credit approval. Before adds three weeks to the front of the process.
Whether the money is committed. A lender with a committed facility behind it can commit to a date. A lender raising funds deal by deal cannot, whatever it says.
The quality of your own pack. A complete submission with planning, drawings, a costed schedule of works, the contractor's details, an assets and liabilities statement and evidenced comparables moves straight to underwriting. An incomplete one sits in a queue while someone chases the missing pieces.
When a bank beats a specialist, and when it does not
Take the bank when:
- You have the equity comfortably and the leverage difference does not change what you can do
- The scheme is conventional, consented and in a mainstream location
- You have time, measured in months rather than weeks
- You already bank there with a genuine relationship
- The scheme is large enough to interest them
- You want the cheapest money and nothing else matters
Take the specialist or the fund when:
- The leverage difference lets you do something you otherwise cannot, and the marginal cost calculation supports it
- The site has a wrinkle: unusual title, part complete, a conversion, an awkward planning history
- You are a first time developer, or your track record is in a different scheme type
- The timescale is weeks
- You need certainty of execution more than the best rate
Take the private or family office lender when:
- Speed is the point and nothing else will move fast enough
- The scheme needs a view taken rather than a box ticked
- You expect to need flexibility during the build and want to deal with a decision maker rather than a process
The honest cases where the cheaper rate is the wrong answer
When the cheap facility does not complete in time. A better rate you do not get is worth nothing, and a site lost to a slow lender costs the whole profit, not the rate difference.
When the leverage gap forces a mezzanine layer. A bank at 60% plus mezzanine at 20% a year to fill the gap is usually more expensive in total, and far more complicated, than a specialist at 70% in one facility. Run the blended cost. A joint venture is the other way to fill that gap, and it costs a share of the profit instead of interest.
When the covenants are tighter than the scheme can carry. A lower rate with a cost to complete test you will breach in month six is not cheaper. It is a problem with a discount on it.
When you will need flexibility. If there is any real chance of a variation, an overrun or a delay, the cost of a lender who will not engage quickly exceeds the rate saving. This is the one developers consistently underweight, and it is why the lender types at the top of this page matter more than the pricing table.
Your questions
What is senior debt in development finance?
The first charge facility covering most of the project cost, ranking ahead of everything else. It is the main layer, with mezzanine, joint venture equity and the developer's own money sitting behind it.
How is senior development debt priced?
Usually as a margin over the Bank of England base rate, with published margins across our index running from 4.70% to 6.75%. Private lenders more often quote a flat monthly or annual rate. Converting one into the other is the only way to compare them.
Is a margin over base better than a fixed rate?
It is usually cheaper at the headline and it puts the interest rate risk on you. On a long facility, or where you need certainty for an appraisal, a fixed rate has real value. Check for a base rate floor either way.
How much equity will I need for senior debt?
On a 90% of cost facility, 10% of total project cost, provided the GDV test does not bite first. Banks will want considerably more, often 15% to 20% or beyond.
Is stretched senior worth it?
Work out the marginal cost. On the comparison above, the extra £55,000 of leverage cost 25.9% a year, which is mezzanine pricing arriving inside a senior facility. Whether that is worth paying depends entirely on what the released cash does.
What happens if I breach a covenant?
Usually a reservation of rights letter, a pause on drawdowns, then a waiver for a fee or a requirement for more equity. Enforcement happens where the scheme is not viable, not merely delayed. Disclosing early changes the conversation materially.
Can a first time developer get senior debt?
From specialists and some funds, yes, usually at lower leverage and with an experienced contractor or project manager required. Clearing banks rarely.
How long does senior development debt take to arrange?
Six to twelve weeks is typical, three to four at the fast end, three to six months with a clearing bank. Delegated authority rather than a credit committee is the biggest single factor.
What is the most important clause in the facility agreement?
Arguably the cost to complete covenant, because it is tested at every drawdown and can breach without you doing anything wrong. The negative pledge matters too, because it determines whether you can add mezzanine later.
Which type of lender should I use?
Match the type to the scheme. Banks for cheap money where you have cash and time. Funds and specialists where leverage, speed or an unusual site matter. Private and family office lenders where speed is the whole point. And consider how each type behaves if the scheme slips, because that is where they differ most.
Does the senior lender control whether I can add mezzanine?
Effectively yes. The negative pledge in the senior facility agreement prevents further charges without consent, so the senior lender's consent and the intercreditor deed are the binding constraints, not the mezzanine lender's appetite.
Related
Got a deal like this on your desk?
Tell us the numbers and we'll tell you honestly what's achievable.
Prefer to put it in writing? Email support@bridgingfinancebroker.co.uk