
Equitable Charge Bridging: when your lender says no to a second charge
Your mortgage lender has refused consent for a second charge, and the equity is still sitting there. An equitable charge is the workaround that most borrowers, and plenty of brokers, have never heard of. Here is how it works and when it makes sense.
Talk to Ashley about your deal
An equitable charge is security over property that is not registered as a legal charge. The lender gets a claim against the property, enforceable by a court, but it does not appear in the charges register as a mortgage and no legal estate passes to it. The part that matters commercially: it can be created without the consent of whoever already holds a legal charge.
That single feature is why it exists as a bridging product. Most second charge bridging deals live or die on the first lender's consent. Where that consent is refused, or where it is coming but not quickly enough, an equitable charge is the route that keeps a transaction alive.
It is also weaker security. That is not a quibble, it is the whole trade. Only 4 of the 67 short-term lenders on our index will take one, they price for it, and the enforcement position is materially worse than a registered charge. This page sets out how an equitable charge is created, how it is protected at the Land Registry, where it ranks, how it is actually enforced, who lends on it, and the trap that catches most people, which is nothing to do with the Land Registry at all.
One thing before any of it. We are mortgage brokers, not solicitors. Everything below is the commercial picture as we see it placing these deals, and the law is summarised to the published sources. The documentation on an equitable charge does more work than on almost any other product, so take your own legal advice on the actual paperwork rather than relying on a page like this one.
Legal charge, equitable charge: what actually differs
A legal charge transfers a proprietary interest and is completed by registration at HM Land Registry. The lender's name appears in the charges register. With registration comes a statutory power of sale and, in practice, the ability to appoint receivers and deal with the property without asking a court's permission first.
An equitable charge creates a claim in equity. The property is made available to satisfy the debt, and a court will recognise and enforce that, but no legal estate passes and the charge cannot be entered as a registered charge. It is protected on the register a different way, and that difference runs through everything else on this page.
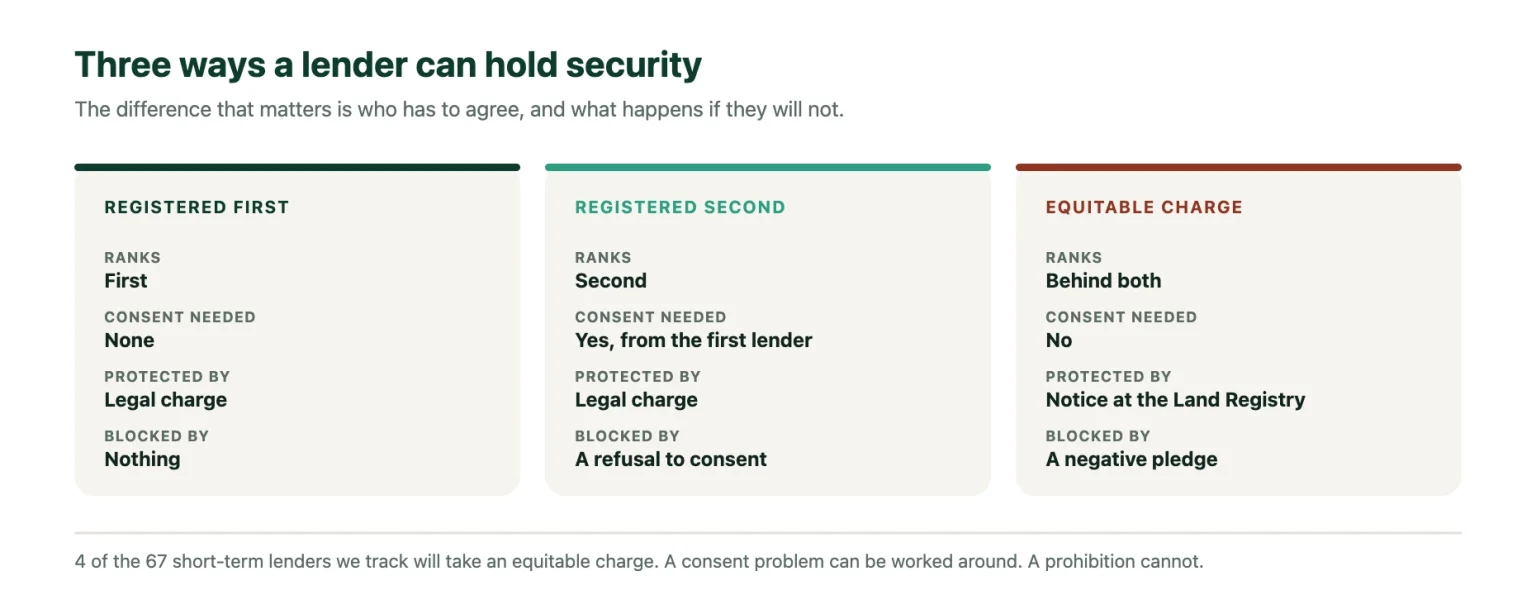
Three consequences follow, and they are the three things worth understanding before you sign anything:
- It can be created without the first lender's consent. This is the benefit, and it is real.
- Its protection on the register is thinner, and in one common scenario it protects nothing at all.
- Enforcement usually means going to court. That is slower, dearer and discretionary.
"People hear 'no consent needed' and stop listening. The sentence they need to hear is the next one. You are buying speed and availability, and you are paying for it in enforcement strength, in choice of lender and in price. If someone sells you an equitable charge as a free workaround, they either do not understand it or they are not telling you."
How an equitable charge is created
By agreement. A written charge, almost always executed as a deed, in which the borrower agrees that a named property stands as security for the debt. This is what a bridging lender takes, and the deed point matters more than it looks, for reasons set out in the enforcement section below.
By an informal arrangement that equity treats as a charge. The textbook example is a deposit of title documents accompanied by an agreement to charge. This is now largely historical. Section 2 of the Law of Property (Miscellaneous Provisions) Act 1989 requires a contract for the sale or other disposition of an interest in land to be in writing, to contain all the expressly agreed terms, and to be signed by both parties. In United Bank of Kuwait plc v Sahib [1997] Ch 107 the court held that a deposit of title deeds on its own, without that writing, no longer creates an equitable mortgage. If anyone suggests handing over deeds as security, that is not a structure, it is a misunderstanding.
By operation of law. Most commonly a charging order obtained by a judgment creditor. Section 3(4) of the Charging Orders Act 1979 provides that a charging order takes effect as an equitable charge, which is why HM Land Registry treats the two in exactly the same way and why its guidance on charging orders is the clearest published account of how any equitable charge is protected.
How it is protected at the Land Registry
This is the section that decides whether the security is worth anything, and it is the section most summaries skate over. An equitable charge cannot be entered as a registered charge. It is protected either by a notice or by a restriction, and which one applies depends on what is actually being charged. The two are not alternatives you get to choose between. They attach to different things and they do different jobs.
Where the charge attaches to the legal estate: a notice. An entry in the charges register, and it is what any competent bridging lender will want. There are two kinds.
An agreed notice is entered either with the registered proprietor's consent, or where the applicant satisfies the registrar that the claimed interest is valid, which normally means producing the executed charge. It is stronger, and it is harder to remove.
A unilateral notice can be entered without the proprietor's consent and without the applicant showing the claim is valid. The registrar only checks that the interest is of a type capable of protection that way. It is quick to get, and it is quick to attack, which is the part to understand.
The registered proprietor, or anyone entitled to be registered as proprietor, can apply to cancel a unilateral notice at any time and without giving a reason. Where there are joint proprietors, each must apply. The registrar then serves notice on the beneficiary, who has 15 working days to object and show an arguable case. Miss that window and the notice is cancelled and the protection is gone. Disputes that are not resolved go to the Land Registration division of the First-tier Tribunal.
Fifteen working days is three weeks. On a twelve month facility with a borrower who has stopped answering the phone, that is a thin thread to hang security on. Get an agreed notice wherever the borrower's cooperation can be had, which means getting it at the outset, while they still want the money.
Where the charge attaches to a beneficial interest: a restriction. Where what is charged is someone's beneficial interest under a trust of land, rather than the legal estate, a notice cannot be used at all. Interests under a trust of land are expressly excluded from protection by notice. The protection is a Form K restriction, applied for on form RX1 with a certified copy of the charge.
And a restriction does not protect priority the way a notice does. Land Registry's own guidance says a restriction should not be used to protect priority where a notice is available. Worse, a Form K restriction is automatically cancelled when a transfer for valuable consideration is registered. The working assumption behind that is blunt: if the debt is still unpaid, the charged interest has been postponed under section 29 of the Land Registration Act 2002 and has come to an end. What survives is a claim against the proceeds of sale, not against the property.
"If your security is a share of a jointly owned house rather than the house, you do not have what you think you have. The property can be sold, the restriction falls away, and you are chasing money instead of holding an asset. I have seen lenders price that structure as though it were the same deal. It is not the same deal."
Where it ranks, and the bit most people get wrong
Priority is more nuanced than the usual summary allows, and the nuance runs in the lender's favour more often than people expect.
The basic rule. Section 28 of the Land Registration Act 2002 says the priority of an interest affecting a registered estate is not affected by a disposition of that estate, and that it makes no difference whether the interest or the disposition is registered. So equitable charges rank between themselves by date of creation, noted or not.
The exception that bites. Section 29 is the exception. Where a registrable disposition of a registered estate is made for valuable consideration, completing it by registration postpones any interest whose priority was not protected at the time of registration. An interest is protected if it is a registered charge or the subject of a notice in the register. So an unprotected equitable charge is defeated by a later legal charge, because the later legal charge is a registrable disposition for value and yours was not on the register.
The bit most people get wrong. A properly noted equitable charge takes priority over a legal charge created afterwards. A legal charge does not automatically outrank an equitable one. If the notice went on first, you rank first. The order and the speed of protection is what determines priority, which means getting the notice entered promptly is not post-completion housekeeping. It is the security.
And the one nobody mentions: further advances. Section 49 of the same Act deals with tacking. A lender holding an existing registered charge can make a further advance that still ranks ahead of your charge in several situations: where it had not received notice of your charge, where it was under an obligation to make further advances and that obligation was on the register when your charge was created, or where a maximum amount the charge secures was agreed and entered on the register at that point. The practical step is simple and it is routinely skipped. Give the first lender formal notice of your charge, because notice is what stops the tacking clock. The irony is not lost on anyone: the structure chosen to avoid asking the first lender's permission works best when you write to the first lender anyway.
Enforcement: what you actually give up
This is the real limitation, and it is substantial. It is also more interesting than the usual flat statement that an equitable chargee has no power of sale, which is not quite right.
The power of sale. Section 101(1) of the Law of Property Act 1925 gives a mortgagee a power of sale "where the mortgage is made by deed". It says mortgagee, not legal mortgagee. So a bridging lender's equitable charge, executed as a deed, is not in the position of a scribbled-down charge with no power of sale at all. An equitable charge created otherwise than by deed, a charging order included, genuinely has no statutory power of sale.
The problem is not the power, it is the conveyance. Having a power of sale and being able to use it are different things. An equitable chargee does not hold the legal estate, so it cannot convey the legal estate to a buyer. The power is real and largely unusable on its own.
Which is what the court is for. On an application for sale the court can act under section 91 of the Law of Property Act 1925, and section 90 then lets it vest a legal term of years in the chargee so it can sell as though it held a legal mortgage made by deed. The practice is a term of 3,000 years on a freehold, or one day less than the remaining term on a lease. That converts the position into a workable one. It also means a court application, costs, and a discretionary outcome rather than an automatic one.
Possession is separate, and harder. An equitable chargee has no inherent right to possession, because it has no legal estate, so possession generally needs a court order too.
Receivers. Available where the charge document expressly provides for it, or by court order. If the document is silent, you are back in court.
The drafting point that makes the difference. A well drafted equitable charge contains an irrevocable power of attorney letting the lender execute a legal charge or a transfer on the borrower's behalf. That is the clause that converts a weak enforcement position into a strong one, because it lets the lender perfect the security into a registered legal charge without needing the borrower to cooperate again, and without the court route above.
If you are borrowing, know the clause is there and understand what it lets the lender do. If you are assessing a lender's documentation, its presence tells you how seriously they have thought about their own position, and its absence tells you something too.
Who lends on it, and on what terms
Four of the 67 short-term lenders on our index will take an equitable charge. Three of those four also do third charges, which tells you the kind of lender this is: the specialist end, comfortable behind other people's debt, pricing for position rather than for prime risk.
| Lender type | Loan size | Max LTV | Rate from | Charges taken |
|---|---|---|---|---|
| A declared second, third and equitable charge specialist | £27,500 to £3m | 75% | 0.75% pcm | 1st, 2nd, 3rd |
| Third-party and equitable charges, all credit histories considered | £50,000 to £5m | 75% | 0.95% pcm | 1st, 2nd, 3rd |
| Mezzanine second charges and equitable charges, mainland Scotland included | £100,000 to £1m | 75% | 0.89% pcm | 1st, 2nd, 3rd |
| A larger lender, equitable charges specifically capped | Capped at £250,000 for this structure | 65% | 0.74% pcm on its other products | 1st, 2nd |
Three things to take from that table, and the third is the one that is usually missed.
The specialists are small-ticket friendly. One starts at £27,500. That is unusually low, and it is what makes an equitable charge viable on a modest raise where the full legal route and a deed of priority would be disproportionate to the money involved.
One lender wants consent evidenced anyway, caps the loan at £250,000 and holds it to 65% loan to value. Sit with that for a second, because it undercuts the main selling point. A lender taking an equitable charge but still requiring the first lender's consent is using the structure to get round the registration step, not the consent process. If avoiding consent is why you are here, that is not the lender for you.
The leverage question is not what it looks like. Three of the four publish a 75% maximum, which is at or above the usual second charge ceiling, where 70% is the normal upper end and 75% is rare and conditional. So the published numbers do not show equitable charges being lent on more cautiously. But those headline figures are the lender's general maximum across its second and third charge range, and the only lender on the panel that states a cap specific to equitable charges pitches it lower, at 65% and £250,000. Read the published maximum as the lender's ceiling, not as the number you will get on this structure, and ask the question directly: what is your cap on an equitable charge, as opposed to a registered second?
On price, expect to pay more than an equivalent legal second charge. The weaker enforcement position is priced, and it should be. As on any bridge, the headline monthly rate is only part of it, and the fee structure usually decides what the facility actually costs. Our bridging loan rates page sets out how that arithmetic works.
The negative pledge trap
Here is the thing that catches people, and it has nothing to do with the Land Registry.
Not needing consent to create a charge is not the same as being allowed to create one. Most mortgage conditions contain a negative pledge: a clause prohibiting the borrower from creating further charges of any kind over the property without the lender's consent. An equitable charge is a charge. Creating one where the mortgage conditions forbid it is a breach of the mortgage, whether or not the first lender's consent was legally required to bring the charge into existence.
What a breach can mean is that the first lender treats the whole balance as immediately repayable. In practice they rarely do that on a loan that is performing and where they get paid. But the risk is real, it is not one to run without advice, and the honest position is this:
An equitable charge solves a consent and registration problem. It does not solve a prohibition problem. Where the first lender has refused consent because its conditions forbid further charges, taking an equitable charge anyway is not a workaround. It is a breach with better packaging.
Where it genuinely works is where the first lender is slow rather than opposed, where its conditions do not prohibit further charges, or where the security is a property or an interest the first charge does not cover at all.
When an equitable charge is the right answer
When the first charge lender is slow, not opposed. The most common case and the best one. Consent is coming but the deadline will not wait. First lender consent on a second charge commonly runs anywhere from a week to six, and a transaction with a fixed completion date cannot absorb the top of that range. The equitable charge completes the deal, and where the document allows it the charge can be perfected into a registered legal second charge once consent lands.
Our half-built house second charge is a case in point on how much the position behind an existing lender shapes what is possible.
When the lease prohibits a legal charge. Some leases restrict charging without the landlord's consent, and an absent, obstructive or simply unfindable freeholder can make a legal charge impossible rather than merely slow. An equitable charge over the leasehold interest is a route through it.
When the security is a makeweight. Where the main security sits elsewhere and this property is additional comfort, the weaker enforcement position matters far less, because nobody expects to enforce against it in isolation. Some lenders will only take an equitable charge in this supporting role, and that is a sensible place for the structure.
When the security is a beneficial interest. Where the borrower owns a share rather than the legal estate, an equitable charge over that share may be the only security available at all, subject to everything said above about restrictions and section 29.
When a third party is providing the security. A parent, a business partner, a company connected to the borrower. Third party security is awkward to document as a legal charge and brings independent legal advice requirements with it. One lender on our panel specifically offers both third party and equitable charges, and that combination is not a coincidence.
When the amount is small relative to the cost of doing it properly. On a £40,000 raise, a deed of priority process costing four figures and taking several weeks is out of proportion to the money. There is a point below which the legal route costs more than it protects.
On a short-dated transaction. A restructuring or a facility that will be repaid in weeks, where perfecting a legal charge is not worth the time it would take.
When it is the wrong answer
When the first lender has refused on the basis of its conditions. Covered above. That is a prohibition, not a process problem, and no structure fixes it.
When it is your primary security. If the equitable charge is the only thing standing behind a substantial loan, the enforcement weakness is the entire risk. A lender willing to accept that position should be asked, politely but directly, why.
When the charge will only ever be protected by a restriction. Priority is not properly protected, a sale for value can bring the interest in the land to an end, and you are left with a claim against proceeds.
When the borrower will not cooperate on an agreed notice. A unilateral notice the proprietor can apply to cancel at any time, without reason, leaving you 15 working days to object, is thin protection on a long facility. If they will not cooperate at the outset, ask yourself what they will be like at the end.
When there is time to do it properly. A legal second charge with a deed of priority is better security, cheaper money and a cleaner position. If you have six weeks, use them. Our second charge bridging page covers the consent process and deeds of priority in detail.
Equitable charge versus legal second charge
| Legal second charge | Equitable charge | |
|---|---|---|
| First lender's consent | Required | Not required to create it |
| How it sits on the register | Registered charge | Notice, or restriction only |
| Power of sale | Yes, without the court | By deed, yes in principle, but the legal estate cannot be conveyed without a court order or a power of attorney |
| Possession | Available to a legal chargee | Generally needs a court order |
| Published maximum LTV | 70% is the usual upper end, 75% rare and conditional | 75% published by three of the four, but the only equitable-specific cap is 65% |
| Pricing | Above a first charge | Above a legal second charge |
| Lenders available | 36 of 67 | 4 of 67 |
| What sets the timetable | The first lender's consent, commonly one to six weeks | Valuation and legals, with no consent step in the chain |
| Negative pledge risk | Resolved by the consent | Remains, and is the main risk to manage |
The honest summary of that table: you are buying speed and availability, and paying for it in enforcement strength, choice of lender and price.
What to check before you sign
Agreed notice, not unilateral, wherever it can be had. The borrower's cooperation is available at the outset, when they want the money. It is not available later.
Establish what is actually being charged. The legal estate or a beneficial interest. The protection, the priority and the value of the security all differ fundamentally, and this is not a detail to discover at enforcement.
Read the first mortgage conditions for a negative pledge before, not after. Your solicitor should do this as a matter of course. The answer changes the advice.
Check for the power of attorney in the charge documentation. It is the clause that makes the security enforceable in practice rather than in theory.
Give the first lender formal notice of the charge. It is what stops further advances tacking ahead of you under section 49.
Plan to perfect it. Where the obstacle was delay rather than refusal, agree at the outset that the charge converts to a registered legal second charge once consent arrives. Some lenders will reduce the rate when it does, and it is far easier to agree that before drawdown than after.
Expect everything else to be normal. An equitable charge does not avoid the valuation, the lender's legal work or the underwriting. It avoids one specific step in one specific place.
Budget for it costing more, not less. The saving is time. It is not money.
"The cases that go well have one thing in common, and it is not the structure. It is that somebody read the first lender's mortgage conditions on day one. Everything else on this page is detail compared with that."
Your questions
What is an equitable charge on a property?
Security over property that is not registered as a legal charge. The lender gets a claim in equity against the property, protected at the Land Registry by a notice or a restriction rather than by registration as a mortgage. No legal estate passes to the lender, which is what makes enforcement harder.
Do I need my existing mortgage lender's permission?
Not to create one. But most mortgage conditions contain a negative pledge prohibiting further charges of any kind without consent, so creating an equitable charge may still breach your mortgage even though it is legally possible without permission. Those are two different questions and both need answering before you proceed.
Can the lender repossess my property?
Not directly, and not quickly. An equitable chargee has no legal estate and no inherent right to possession, so possession generally needs a court order, and a sale usually means applying to court under section 91 of the Law of Property Act 1925. Where the charge includes a power of attorney, the lender may instead perfect it into a registered legal charge first, which changes that position considerably.
Where does an equitable charge rank against my mortgage?
Behind a legal charge that was already registered when it was created. Ahead of a legal charge created after the equitable charge was properly noted. Priority turns on the order of protection, not on whether a charge is legal or equitable, which is the point most summaries get wrong.
Is a unilateral notice as good as an agreed notice?
No. The registered proprietor can apply to cancel a unilateral notice at any time without giving a reason. The Land Registry then serves notice on the lender, who has 15 working days to object and show an arguable case, or the notice is cancelled and the protection goes. An agreed notice is harder to remove.
How much can I borrow on an equitable charge?
Three of the four lenders on our index publish a 75% maximum and one caps equitable charges specifically at 65% and £250,000. Loan sizes across the four run from £27,500 to £5m. Treat the published maximum as a ceiling rather than a quote, and ask each lender what its cap is on this structure rather than on a registered second charge.
Is an equitable charge more expensive?
Generally yes, reflecting the weaker enforcement position. You are paying for speed and for the ability to proceed without consent. As with any bridge, the arrangement fee, the exit fee and whether interest is retained or serviced usually matter more to the total cost than the headline monthly rate.
Can an equitable charge become a legal charge later?
Yes, and frequently it should. Where the obstacle was delay rather than refusal, the charge can be perfected into a registered second charge once consent arrives. Agree that at the outset and ask whether the rate drops when it happens.
Can I use one on a property I only part-own?
An equitable charge can attach to a beneficial interest under a trust of land, protected by a Form K restriction rather than a notice. But a restriction does not protect priority the way a notice does, and a Form K restriction is automatically cancelled when a transfer for valuable consideration is registered, on the assumption that the interest has been postponed under section 29 and has come to an end. What is left is a claim against the proceeds. It is materially weaker security and should be priced and understood as such.
Can I sell my house with an equitable charge on it?
Yes, but it has to be dealt with. Where the charge is noted against the legal estate, a buyer's solicitor will require the notice removed, which means the debt is repaid or the lender agrees a release on completion. Where it attaches to a beneficial interest and is protected by a restriction, registration of the sale cancels the restriction and the lender's claim shifts to the proceeds.
Is an equitable charge bridge regulated?
The same test applies as to any bridge. It is regulated where the borrower is an individual and at least 40% of the property is, or is intended to be, occupied by the borrower or a close family member, unless a business purpose exemption applies. Our regulated bridging page covers the test, and our tax bills and business use page covers the business purpose exemption.
Why do so few lenders offer it?
Because the enforcement route is slower, more expensive and discretionary, and because a charge protected only by a restriction can be extinguished by a sale. Four of the 67 lenders we track (our wider panel runs to over 120 lenders across all product types) will take one. That scarcity is itself information about the structure.
Got a deal like this on your desk?
Tell us the numbers and we'll tell you honestly what's achievable.
Prefer to put it in writing? Email support@bridgingfinancebroker.co.uk